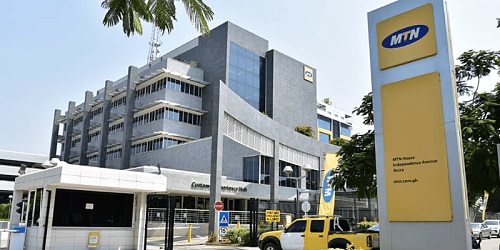
MTN Ghana: Snapshot & Recent Performance
-
MTN Ghana reported a profit after tax of GH¢ 5.0 billion for 2024, up ~26% year-on-year.
-
Service revenue for 2024 grew around 34.5%, driven by data, mobile-money (MoMo) and digital services.
-
In Q1 2025 the company posted a profit of GH¢ 1.7 billion (a ~53.7% increase) with service revenue up ~39.4%.
📢 GET DETAILED ARTICLES + JOBS
Join THSB's WhatsApp Channel and never miss a post or opportunity.
📲 Join THSB Channel Now -
For the first nine months of 2025: service revenue up ~36.3%, profit after tax up ~45.9% to GH¢ 5.5 billion.
-
Dividend: For 2024, total dividend per share is 0.305 GH¢ (or 30.5 pesewas) which is an increase of ~35.6%.
Key Strengths
-
Strong growth engine — MTN’s pivot toward data, fintech (MoMo) and digital services is paying off. As one report notes: “Data now contributes over half (52.6 %) of total service revenue” in Q1 2025.
-
Market leadership — As the leading telecom provider in Ghana, MTN Ghana enjoys scale and strong brand recognition.
-
Dividend-oriented — With a high payout ratio (~80% of profit for 2024), the share offers cash return to shareholders.
-
Macro tailwinds — The Ghana economy is showing improving macro fundamentals (lower inflation, currency stability, etc), which supports consumer spending, mobile uptake and telecom growth.
Major Risks & Considerations
-
Macro-economic risk — Ghana is still exposed to inflation, currency depreciation, and external pressures. As MTN itself noted: “…the macroeconomic outlook for Ghana in 2025 is expected to remain challenging due to the risks associated with elevated inflation and currency depreciation.”
-
Valuation and market risk — While MTN is growing strongly, telecom is a mature sector and growth expectations are already high, which leaves less margin for error.
-
Regulatory/competitive risk — Telecom sectors face regulatory changes (e.g., spectrum costs, licensing), intense competition, and technology disruption (5G, etc).
-
Operational execution — Growth in data and fintech is dependent on successful rollout of network infrastructure, service innovation and cost control. For example, capital expenditure is noted in Q1: GH¢ 1.2 billion, expansion of 4G coverage to 99.3 %.
Outlook & What to Watch
-
If MTN Ghana can sustain 30-40%+ growth in data and fintech segments and maintain margin expansion, the share could continue to deliver strong returns.
-
Dividend persistence is a positive: consistent payouts attract income-seeking investors.
-
Watch macro indicators: inflation, exchange rate & consumer spending. A setback there could hit profitability.
-
Watch valuation expansion: If investor sentiment warms (e.g., more foreign capital into Ghana equities), the stock could re‐rate.
-
Monitor competition & tech disruption: Growth in fintech/mobile money is promising but can attract new entrants or require heavy investment.
Recommendation: Buy, Hold or Sell?
Based on the above, my view is:
-
Recommendation: HOLD → BUY (with caveats)
-
For investors already owning MTN Ghana, holding makes sense: the business fundamentals are strong, growth is visible, dividend yield is attractive, and macro tailwinds are supportive.
-
For new investors: I lean toward Buy, but with caution. The stock looks like a good medium-term opportunity (3-5 years) if you believe in Ghana’s macro-recovery and MTN’s growth trajectory.
-
However, if you are risk-averse or short-term oriented, waiting for a correction or clearer macro stability may be prudent.
-
In summary — MTN Ghana is not a speculative high-flyer with large unknowns; rather it is a well-executing, large-cap Ghanaian stock with both growth and income characteristics. The biggest gamble is national macro/rate/currency risk. If you believe Ghana’s improving story holds, then “Buy and Hold” is the preferred approach. If you’re focused on the next 6-12 months only, you might treat it as a Hold until more macro certainty unfolds.
Source: The High Street Business
Disclaimer: Some content on The High Street Business may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. The High Street Business is a subsidiary of SamBoad Publishing under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.
Samuel Kwame Boadu is a Ghanaian entrepreneur, writer, and digital consultant passionate about creating impactful stories and business solutions. He is the Founder & CEO of SamBoad Business Group Ltd, a dynamic company with subsidiaries in digital marketing, logistics, publishing, and risk management.